When it is a matter of accumulating wealth from investments, keeping taxes as low as possible is as important as attaining high returns. Tax harvesting is one of the smartest strategies available to equity mutual fund investors in India. Not only does this method assist in minimising tax outgo, but it also helps you in achieving maximum gains within the limit allowed. If you’re designing your long-term capital gains (LTCG) and seek pragmatic income tax advice, having knowledge of tax harvesting in mutual funds may be enormously beneficial to you.
What is Tax Harvesting?
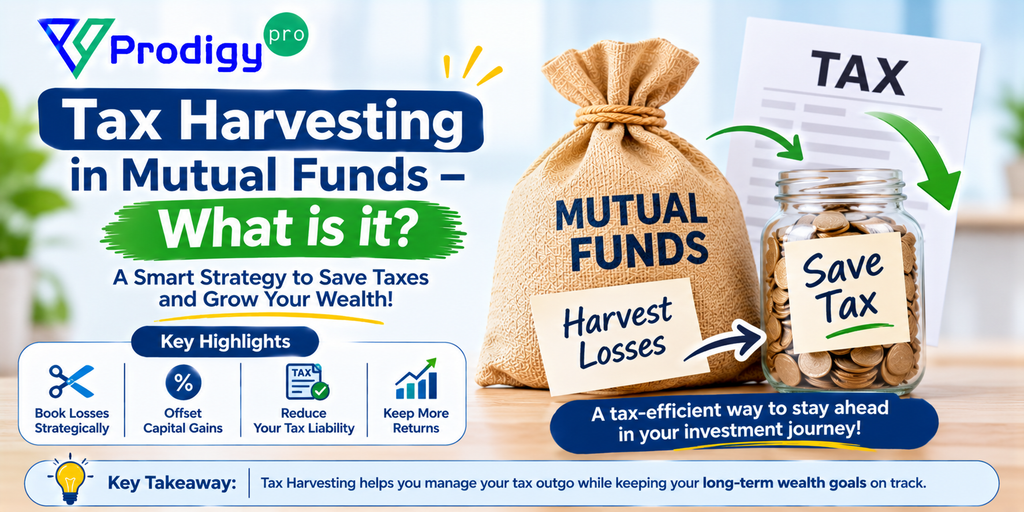
Tax harvesting is a disciplined portfolio management strategy through which investors sell specific equity mutual fund units, to intentionally realise either capital losses or gains. It aims to reduce the total tax burden, especially that of long-term capital gains. The investor can repurchase the same or other units of the fund once it has been sold to maintain the same investment holding. By resetting the purchase price (Net Asset Value or NAV) of the investment to a higher current level, the investor reduces future taxable capital gains without reducing their overall market exposure.
Technically, tax harvesting does not alter your underlying asset allocation or long-term financial goals; it is a tactical tax-planning manoeuvre designed to optimise the timing of gain recognition for maximum tax efficiency.
Understanding LTCG and Why it Matters
Before proceeding with tax harvesting, you should know about Long-Term Capital Gains (LTCG). In India, if your equity mutual funds are held for over one year, any gain in excess of ₹1 lakh in a financial year is LTCG and is taxed at 10%. This provision makes it necessary for the investor to decide when and how the mutual funds are going to be sold.
Assume you have made a profit of ₹90,000 from your mutual fund investments in a financial year. If you redeem the units, your profits are tax-free because they are below ₹1 lakh. However, if your profits exceed ₹1 lakh—let’s assume it is ₹1.5 lakh—you’d be charged 10% of the ₹50,000 surplus.
This is where LTCG planning and tax harvesting come in, helping you save tax by making the most of the annual exemption threshold for your gains.
How Tax Harvesting in Mutual Funds Works
Check Your Portfolio
Begin by taking a look at your equity mutual fund portfolio. See which investments have gained in value and are approaching or even surpassing the ₹1 lakh LTCG exemption limit. Ensure units are checked on a FIFO (First-In, First-Out) redemption basis.
Sell Smartly
If your capital gains are close to the exemption threshold, you can sell enough mutual fund units to keep your gains below ₹1 lakh. This way, your gains remain entirely tax-exempt for that financial year.
Reinvest to Remain Invested
Reinvest the redeemed proceeds back into equity mutual funds to maintain your target asset allocation. To avoid market gap risk or NAV timing delays, investors can switch into a peer fund within the same category (e.g., another Large-Cap or Flexi-Cap fund) or repurchase the same fund after funds settle.
Use Losses to Counterbalance Gains
If you are experiencing capital losses in other investments, for instance, losing funds in underperforming stocks or mutual funds, you can liquidate them in order to absorb gains in your performing investments. This decreases the overall taxable capital gains.
Tax Harvesting vs. Conventional Investing
Traditional investing sees you keeping your investment long term without intentionally managing taxation. Tax harvesting is a bolder method wherein you manage your gains to receive maximum tax benefits. It will not disrupt your long-term investment strategy. You get to retain the performing assets because you re-buy them, but you do that while managing tax efficiency.
Principal Advantages of Tax Harvesting
- Tax Saving: By keeping below the ₹1 lakh LTCG exemption limit annually, you avoid paying 10% tax on gains.
- Increased Returns: With each passing year, all such savings pile up cumulatively, further enhancing your portfolio’s net return.
- Portfolio Balancing: It provides you with an opportunity to study and realign your asset proportions.
- Maximum Loss: Selling loss-incurring stocks gives you an opportunity to offset profits elsewhere.
- Tax Record Keeping and Minimisation of Waste: It helps you maintain improved tax files and optimally utilise rightful reductions.
Tips to Maximise the Utilisation of Tax Harvesting
- Plan Ahead: Postpone it until the end of the financial year. Monitor profits periodically.
- Use the ₹1 Lakh Limit Judiciously: In case your gains are approaching the exempted limit, sell and revalue your basis for the following year.
- Maintain Investment Holding Period in Check: Ensure that investments sold to qualify for LTCG have been held for more than one year.
- Reinvest with Caution: If your mutual fund has an exit load or if the NAV fluctuates, it can affect your decision to reinvest.
- Consult an Advisor: Professional guidance helps in executing tax harvesting efficiently, especially for large portfolios.
When is Tax Harvesting Most Effective?
Tax harvesting is most effective when:
- You’ve had a good year in the markets, and your equity fund investments have significantly appreciated.
- You have unused LTCG exemption and would like to utilise it to the fullest.
- You have unrealised losses in other investments that can be used to offset taxable gains.
- You are nearing the end of the financial year and are in a hurry to make tax-saving choices.
Common Mistakes to Avoid
- Overlooking Transaction Costs: While buying and selling, consider the brokerage and exit load. While exit load is zero after 1 year, fresh purchases incur a minor 0.005% statutory mutual fund stamp duty. Factoring in this negligible cost ensures accurate net gain calculations.
- Frequent Trading: This is not a situation of frequent buying and selling—it’s a yearly or one-time move.
- Ignoring Reinvestment Risk: Unless the NAV remains relatively stable between selling and reinvesting, fluctuations during this period could cause you to miss out on potential value.
- Lack of Documentation: Keep clear records of all sale and repurchase transactions for income tax filing purposes.
Final Thoughts
Tax harvesting is no loophole or gimmick—it’s a real financial planning technique that operates within India’s income tax regime. By learning about and applying tax harvesting to mutual fund investments, you can save hundreds of rupees in taxes, receive the advantage of the ₹1 lakh LTCG exemption, and optimise the overall well-being of your investment portfolio.
It’s a subtle yet powerful way to ensure that your wealth grows not only by investing smartly but also by managing your tax obligations efficiently. Combine this with other income tax tips, and you’ll be on a solid path to financial independence.
Disclaimer – This article is for educational purposes only and does not intend to substitute expert guidance. Mutual fund investments are subject to market risks. Please read the scheme-related document carefully before investing.
FAQs
1. What is the LTCG exemption limit under Indian tax laws?
The exemption limit for long-term capital gains on equity mutual funds is ₹1 lakh per financial year.
2. Can I reinvest the moment I redeem units of a mutual fund for tax harvesting?
Yes, you can reinvest in the same or in a comparable fund. But take care of exit loads and price volatility.
3. Is tax harvesting for small investors only?
Absolutely. Even if your portfolio is not big at all, utilising the ₹1 lakh LTCG exemption intelligently every year can accumulate massive savings in the long run.
4. Can I get short-term capital losses for tax harvesting?
Yes, short-term capital losses are available to offset short-term and long-term gains and can legally be utilised in tax planning.
5. Is tax harvesting illegal?
No, tax harvesting is entirely lawful and is a part of intelligent investing and tax planning best practice.