Saving is no longer an “adult thing”; the new generation is showing interest in financial planning even from their teenage years. When you first start earning, managing money can feel like a tough topic, but believe us, it is one of the most serious, exciting, and powerful things to understand. Whether you are a high school student, a college student, or have been working for more than 5 years, it is never too late to start your financial planning with a monthly financial checklist.
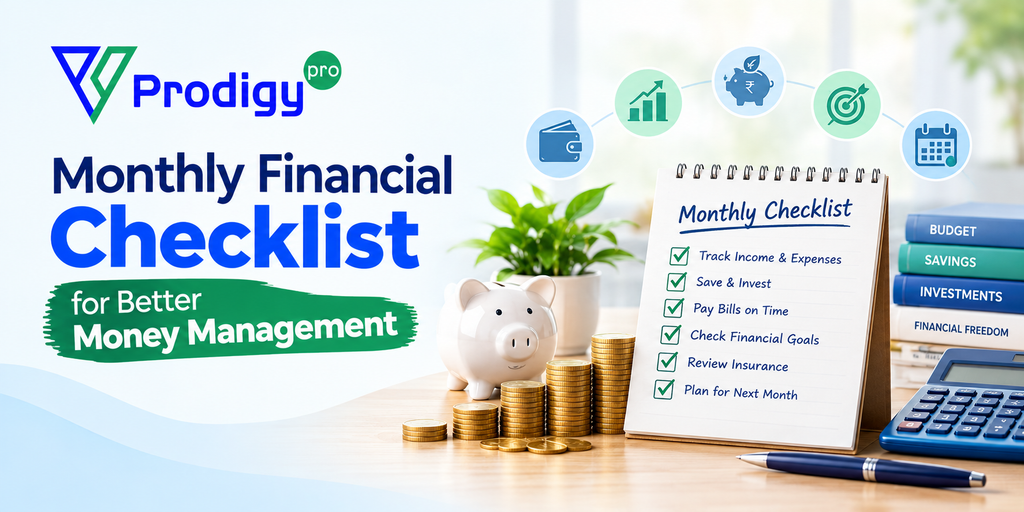
This money management checklist is a simple personal finance checklist that India can use every month. It works as a monthly budget planner too, and it is especially handy as a financial checklist for salaried employees.
Your Monthly Financial Checklist at a Glance
| Step | What to do |
| 1. Review spending | Check where last month’s money went. |
| 2. Update budget | Plan next month using the 50/30/20 rule. |
| 3. Pay yourself first | Automate a SIP on salary day. |
| 4. Check balances | Track bank, card, UPI, and investment accounts. |
| 5. Emergency fund | Build a separate financial safety net. |
| 6. Credit score | Check your credit report every few months. |
| 7. Debt | Track EMIs, interest rates, and due dates. |
| 8. Invest | Start learning about the market and invest small amounts. |
The 8-Step Financial Checklist You Need
- Review your spending from last month.
Before you start making a checklist, you must look back and check exactly where you spend money. Ask yourself 3 questions:
- Did you stay within your budget?
- Where did you spend too much?
- Identify unplanned expenses.
You can identify the exact spending from your bank statement or in the payment apps. Once you do it, try to control spending on that particular category. Remember, better money management always comes from limiting your overspending.
- Pay yourself first: automate your salary on SIP date.
This is the step most people skip. Instead of saving whatever is left at the end of the month (spoiler: usually nothing), move your savings first. Set up a Rs 500–Rs 1,000 SIP to go out right after your salary is credited. Saving what’s left over rarely works; paying yourself first does, because the money is invested before you can spend it.
- Update your next budget.
Once you are done with identifying your last month’s spending, it is time to create your budget for the upcoming month, which changes with time and circumstances.
- Check if you received any extra income through a salary hike, a bonus, or from any side hustle.
- Look at your variable expenses like groceries, electricity bill, dining out, etc.
- Look at your fixed expenses like insurance, rent, internet, etc.
- Check your debt payments like EMI, credit card bills, and others.
At this stage, one should always follow the 50/30/20 rule. According to financial advisors, 50% should be spent on your basic needs, 30% is for your wants, and the remaining 20% is for your savings.
- Start learning the stock market.
Curious about investing? Good, but don’t jump in blind. Equity returns aren’t guaranteed, and prices can fall, especially in the short term. However, starting early gives your money more time to weather fluctuations and benefit from compounding, where your returns begin to generate their own returns.
If you’re a beginner, start small with a SIP in a diversified equity mutual fund, and learn the basics first: how markets work, what risk and diversification mean, and how to read a fund’s factsheet.
- Keep tracking your account balance.
Since people have started using payment apps, the habit of overspending is rapidly increasing. Therefore, it is becoming more difficult to control savings. Many of you might feel tense while checking the account balance, because no one prefers to see less than expected. But when you make a habit of checking your account, credit card usage, savings account and investment account, you become more conscious about your spending.
- Plan for an emergency fund.
When you are investing, make sure you have special savings for emergency purposes. In today’s generation, Health insurance is commonly provided by the corporate offices, but apart from that make sure you have a separate savings account for any unwanted situation. These surprising and unwanted situations can include getting laid off from your job, or big car repair expenses can arise at any time.
- Check your credit report.
Along with checking your account balance, it is also equally important to check your credit report. But unlike the account balance, you don’t have to check your credit report every month. Just doing it quarterly or every few months will be enough. There are a lot of free websites available to monitor your credit, so check them accordingly.
- Track your debt.
If you make a habit of tracking your debt every month, it will always help you to make your checklist for money management in an organised way. Check your interest rates, current balance, any extra payments, and also payment due dates. Handle your debts carefully.
It’s a wrap
Have you stuck to your budget? Have you saved more than you expected? Great, time for a celebration! Always reward yourself in a small and meaningful way, because you are doing something that most people avoid. Making a financial checklist isn’t mandatory for all but you should make it a habit just like laundry and cooking because it is going to show you the result in the near future. So be consistent.
Please share your thoughts on this post by leaving a reply in the comments section. Contact us via Phone, WhatsApp, or Email to learn more about mutual funds, or visit our website. Alternatively, you can download the Prodigy Pro app to start investing today!
Disclaimer – This article is for educational purposes only and does not intend to substitute expert guidance. Mutual fund investments are subject to market risks. Please read the scheme-related document carefully before investing.
FAQs
- Why does the financial checklist matter?
The financial checklist matters to reduce your financial stress, track your progress to stay organised and also to avoid missing the key deadlines and responsibilities.
- How often should one review their financial checklist?
The review of the financial checklist should be done monthly or quarterly.
- What are the essential components of a financial checklist?
The essential components of a financial checklist are savings, budgeting, investment review, insurance coverage, goal setting, and debt management.
- How much must one save every month?
20% is a common amount to save from your income.
- What types of savings must one have?
Everybody should have savings, starting from an emergency fund to retirement savings, savings for short-term goals like travel and down payments.