Financial planning for newly married couples
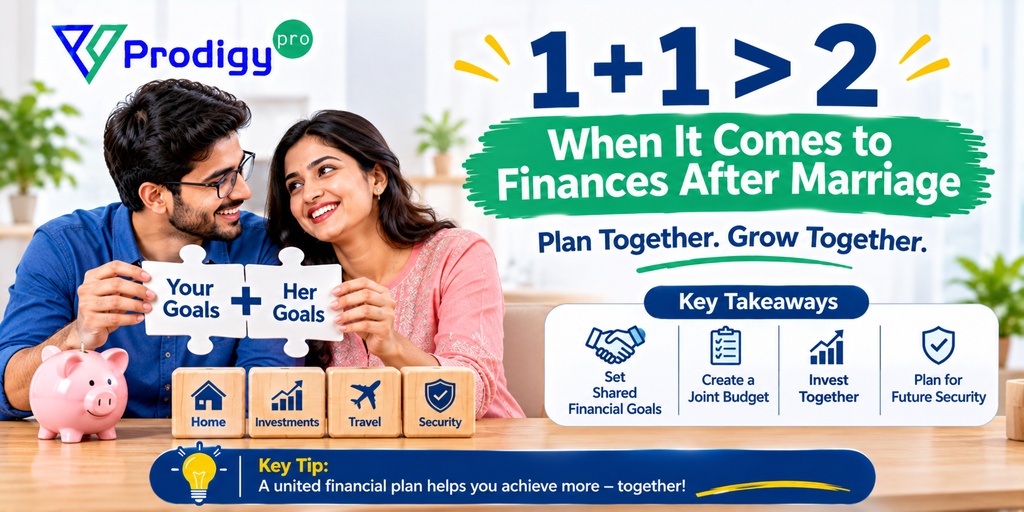
When two people get married, they share visions, responsibilities, and one of the most difficult aspects: money. Love is the starting point, but financial clarity is what builds a secure future together. With proper financial planning, the combined financial strength of a couple can be greater than the sum of its parts. That is, you can indeed make 1+1 > 2 with good budgeting.
Let us discover how financial planning for newly married couples can create long-term wealth when properly planned.
Why Is Financial Compatibility Important?
Financial compatibility is not about having the same pay scale or identical ways of spending. It is about sharing similar values regarding spending, investing, saving, and risk-taking. Couples need to have open conversations about:
- Income and expenses
- Debt payments
- Credit reports and financial history
- Long-term goals (buying a home, raising kids, vacation, retirement)
- Investment philosophy and risk appetite
Transparent communication at the beginning gives confidence and becomes the foundation for achieving shared financial objectives.
Step 1: Create a Joint Financial Map
Set Common Goals
Define your goals and milestones together.
- Short-term: Vacation, creating an emergency fund, rental expenses
- Medium-term: Purchasing a vehicle, funding a business setup
- Long-term: Buying a home, children’s education, retirement planning
Goal-based investing enables you to allocate purpose to every rupee, making the process disciplined and meaningful.
Discuss Risk Appetite
Do you and your spouse prefer low-risk investment strategies, or is one of you comfortable with market volatility? Align your risk tolerance so that your joint investment strategy remains comfortable for both of you.
Step 2: Embrace Joint Investment
After having your risk profile and objectives in place, you’re ready to delve into joint investment opportunities. Mutual funds are a good place to start as they can suit various needs and risk appetites.
Types of Mutual Funds to Consider
- Equity Funds: Higher long-term returns; ideal for long-term goals such as retirement or wealth creation.
- Debt Funds: Lower risk and stable returns; ideal for short to mid-term financial needs.
- Balanced / Hybrid Funds: Combination of equity and debt; suitable for moderate risks with reasonable returns.
- Tax-Saving Funds (ELSS): Offers equity exposure with a mandatory 3-year lock-in period. Tax deduction benefits under Section 80C (up to ₹1.5 lakh) apply strictly under the Old Tax Regime. (Note: Section 80C deductions are not available under the default New Tax Regime).
Build a Balanced Mutual Fund Portfolio
Diversification across fund categories helps to minimise risk. Key factors to evaluate include:
- NAV (Net Asset Value): Represents the per-unit price of the fund. Note that a lower NAV does NOT mean a fund is ‘cheaper’ or better; performance depends on the underlying assets’ growth, not the NAV level.
- Fund Performance: Evaluate long-term performance against benchmark indices rather than focusing solely on short-term returns.
- Expense Ratio: A lower percentage means lower management fees, allowing a greater portion of returns to compound over time.
- Asset Allocation: Determine the appropriate split between equity, debt, and gold based on your target timeline and risk tolerance.
Step 3: Prioritise Emergency Funds and Insurance
Ensure you have secured the foundational financial safety nets before making long-term investment commitments:
- Emergency Fund: Maintain 3 to 6 months of your living expenses in liquid instruments such as savings accounts or liquid mutual funds.
- Health Insurance: Ensure adequate floater health cover for both you and your spouse to protect against unexpected medical costs.
- Life Insurance: A must-have if you have financial dependents or joint liabilities such as a mortgage.
Step 4: Simplify Joint Budgeting
With combined finances, track both your incomes and expenses with collaborative budgeting tools like Google Sheets, Notion, or other finance apps. Discuss and decide:
- How much to allocate towards household expenses?
- How to split bills (proportionally based on income or 50/50)?
- How much to allocate towards common goals and investments?
A shared financial roadmap promotes financial discipline and removes potential conflict.
Step 5: Plan Joint Investment
After setting up your financial foundation, transition from passive saving to an active, disciplined investment plan:
- Automate monthly investments through SIPs (Systematic Investment Plans).
- Periodically review your portfolio to monitor progress.
- Adjust your asset allocation periodically to ensure it aligns with your changing risk profile and timeline.
- Long-term investment is the secret of compounding returns. Stay invested through market cycles to maximise wealth creation.
Bonus: Tax Planning as a Couple
Utilise tax-saving options to the maximum:
- If opting for the Old Tax Regime, both spouses with taxable income can individually invest up to ₹1.5 lakh in ELSS funds, claiming combined Section 80C deductions of up to ₹3 lakh.
- Distribute investments between spouses if you and your spouse are in different tax slabs and reduce total tax liability legally.
- To claim joint home loan tax benefits, both spouses must be registered co-owners and co-borrowers actively paying the EMIs. Under the Old Tax Regime, both can individually claim up to ₹2 lakh on interest (Sec 24b) and ₹1.5 lakh on principal repayment (Sec 80C).
Tax planning is beneficial as it allows you to keep a greater portion of your income and hold onto your wealth organically.
Conclusion
Marriage changes your life, and your money. But if managed with the right mindset and game plan, it can be the gateway to monumental wealth building and financial freedom. From creating a cash cushion to holding a well-balanced portfolio of mutual funds, every step counts. Be truthful, pursue goal-based investing, and exhibit financial self-discipline so that your marriage emotionally uplifts, but also financially strengthens you.
For when it’s done right, 1+1 in a marriage doesn’t add up to 2, it adds up to so much more!
Please share your thoughts on this post by leaving a reply in the comments section. Contact us via Phone, WhatsApp, or Email to learn more about mutual funds, or visit our website bfccapital.com.
Alternatively, you can download the Prodigy Pro app to start investing today!
Disclaimer – This article is for educational purposes only and does not intend to substitute expert guidance. Mutual fund investments are subject to market risks. Please read the scheme-related document carefully before investing.
FAQs
Q1: Must we merge our finances entirely after marriage?
No, both of you can have individual accounts of your own and a single joint account for all your shared expenses and goals. It’s whatever fits your relationship.
Q2: Must we invest in mutual funds as a newlywed couple?
Yes. Mutual funds provide a variety of options to suit different risk profiles and objectives. The sooner you invest, the more effective compounding is.
Q3: How do we choose our risk appetite?
Discuss your financial timelines, financial liabilities, and emotional comfort with market swings. If your risk profiles differ, hybrid/balanced funds or a core-satellite strategy can bridge the gap.
Q4: How do we allocate investments as a couple?
If incomes differ, contributing a fixed percentage of each person’s salary (e.g., 20% each) is often fairer than an equal 50/50 split. Automating through SIPs ensures consistency.
Q5: What do we look at when choosing mutual funds?
Take into consideration NAV, performance, expense ratio, portfolio holdings, and track record. Don’t only follow past performance. Make sure the fund suits your purpose.
Q6: Is there any need for us to budget as a couple?
Yes. Budgeting enables one to monitor expenses, save wisely, and not overspend. It brings accountability and financial peace.
Q7: Can we both invest in ELSS funds to save tax?
Yes, provided both spouses have taxable income and choose the Old Tax Regime. Each spouse can claim up to ₹1.5 lakh under Section 80C (totaling ₹3 lakh). ELSS tax benefits do not apply under the New Tax Regime.
Q8: What’s something we need to do as newlyweds so our money grows?
Start small but remain consistent. An SIP in a well-performing equity fund can give you massive returns in the long run. Remain consistent and review periodically.