Quant Mutual Funds
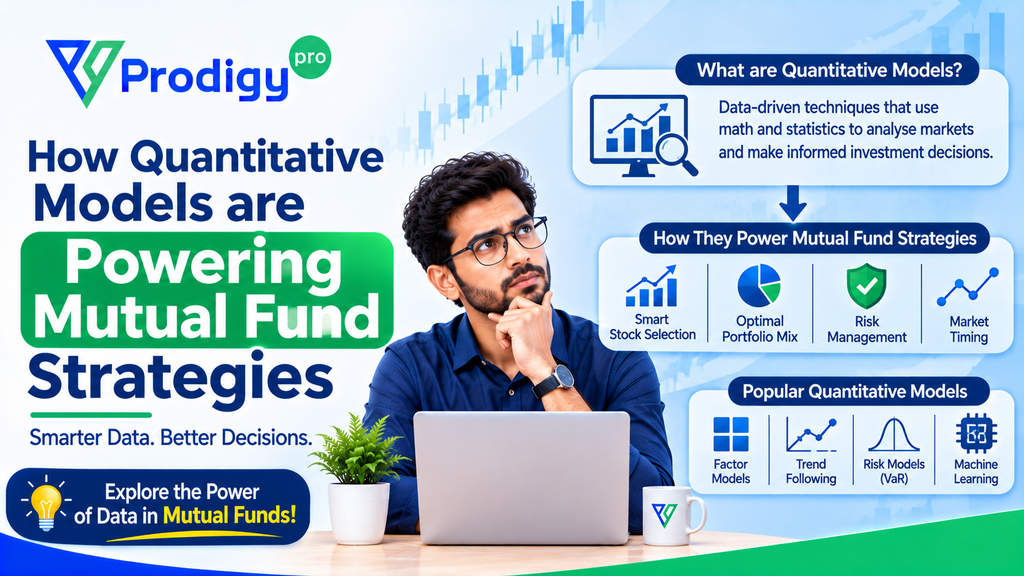
Quant Mutual Funds are a type of fund that seek to provide superior returns by using quantitative models and algorithms. Unlike conventional mutual funds, where investment choices largely depend on human judgment and market insight, quant funds use mathematical models, statistical methods, and historical data to inform their investment approaches.
Fund managers at Quant Mutual Fund use pre-established models to spot investment opportunities. Such models can analyse intricate data quickly and precisely, helping detect patterns and trends beyond human capability.
Quantitative Investing in India
Quantitative investing, commonly called “quant investing,” uses mathematical models, statistics, and algorithms to make investment decisions rather than relying solely on human intuition. In India, this type of investing has attracted a lot of attention in recent years due to improving technology, increased availability of data, and changing market dynamics. In quantitative investing, strategies are built around analysing huge volumes of historical and real-time data to find patterns, relationships, and trends.
Algorithm Mutual Funds
Algorithm mutual funds are mutual funds that apply pre-set rules, mathematical formulas, and computer algorithms to invest in portfolios. Rather than relying on human fund managers based on experience or instincts to select stocks, algorithm mutual funds utilise algorithms to determine investment decisions.
The algorithms are constructed based on data such as share prices, balance sheets, economic indicators, and even technical charts.
Quantitative Models in Fund Management
Quantitative models are now a standard part of contemporary fund management, providing systematic decision-making methods that heavily depend on mathematical, statistical, and computational methods. Popular techniques include factor investing (e.g., aiming at value, momentum, or size factors), statistical arbitrage, and risk parity. Models can also include machine learning algorithms to evolve with changing market patterns over time.
Factor-Based Investing: A Transparent Approach to Smarter Portfolios
In an overcrowded world of black-box investment strategies and AI-powered “magic formulas,” investors are longing for a return to something plain, transparent, and proven: factor-based investing.
Factor investing is about grasping the shared drivers of asset returns and applying them constructively to create more resilient portfolios. Rather than sitting back and trusting in enigmatic algorithms or opaque models, factor-based approaches are constructed on thoroughly documented, rational patterns that have withstood the test of time.
Smart Beta Mutual Funds
Smart beta mutual funds blend the best of conventional passive investment and active management. Rather than attempting to replicate a market-cap-weighted index such as the S&P 500, smart beta funds employ alternative methods (or “rules-based” techniques) to select and weight investments. Smart beta funds seek to beat conventional benchmarks by emphasising certain “factors” that academic studies have associated with greater returns in the long term.
Common factors include:
- Value (stocks that are undervalued relative to fundamentals).
- Momentum (stocks with strong recent performance).
- Quality (companies with strong profitability and balance sheets).
Data-Driven Fund Strategies:
Data-driven fund strategies rely heavily on vast quantities of financial, economic, and alternative data to guide investment choices. Instead of using mostly human instinct or traditional analysis, these strategies use data science, machine learning, and quantitative models to create more intelligent portfolios.
What is Machine Learning in Mutual Funds?
Machine learning (ML) refers to algorithms that enable systems to learn from data, identify patterns, and predict without programming. In mutual funds, ML can be used to sift through vast amounts of data, including historical prices, account statements, social media sentiment, and economic data, to guide investment.
Important Ways ML is Applied in Mutual Funds
1. Predictive Analytics
ML algorithms can forecast future price movements of the assets using past data. This assists the fund managers in anticipating possible returns and risk. With the application of methods such as regression models, the system foretells stock prices or trends in the market within short- or long-term intervals.
2. Algorithmic Trading
ML is employed to develop trading algorithms that are able to examine market conditions and automatically place trades when specified criteria are reached. The algorithms are capable of responding faster than a human being, analysing millions of pieces of data in real-time.
Rule-based investing and quantitative analysis are two investment techniques that have close connections to each other. Both use systematic, data-driven methodologies to make choices. Below is a simple explanation of the two:
1. Rule-Based Investing
Rule-based investing is an investment strategy where the decisions made about when, where, and how to invest are governed by a set of predefined rules. These rules are usually based on some criteria or metrics that determine whether to buy, hold, or sell an investment.
2. Quantitative Analysis in Investing
Quantitative analysis (quant analysis) is the application of mathematical models, statistical methods, and extensive data sets to analyse financial markets and securities. Quant analysis entails assessing numbers, as opposed to subjective judgment or qualitative analysis (such as management quality, market trends, etc.).
AI in Mutual Fund Management is a new discipline with enormous growth potential that is revolutionising the mutual fund management paradigm. Artificial Intelligence (AI) is increasingly used today to enhance investment-making decisions, risk management, and customer interaction in mutual fund operations.
Backtesting is a critical component of investment strategy design and testing. Backtesting is the act of implementing a trading or investment strategy on historical data to see how it would have performed in the past. Backtesting is performed with the objective of understanding how a strategy can perform under different market conditions and identifying potential strengths and weaknesses prior to the strategy being implemented in actual markets.
Quantitative (Quant) Funds use mathematical formulas, algorithms, and statistics to select investments, relying primarily on information and computing power. Return analysis on these funds involves evaluating the fund’s performance on a profitability basis, as well as on a risk basis, considering various metrics and benchmarks.
What Are Multi-Factor Models?
In mutual funds, multi-factor models are employed to construct portfolios by choosing securities that rank high on several factors. These factors may be such attributes as value, momentum, size, volatility, quality, and so on. The rationale is that by combining these factors, one can create a more diversified and stronger investment approach.
Quantitative (Quant) Funds vs. Traditional (Actual) Mutual Funds
The chief distinction between quantitative (quant) funds and normal mutual funds lies in the approach to investment philosophy, decision-making approach, and tools for selection of investments.
Momentum Strategy in Mutual Funds
A momentum approach to investing is the practice of investing in securities with recent good performance, hoping those assets will preserve their performance from the short term to the medium term. Such a strategy assumes that asset prices tend to repeat themselves for a period of time, and those assets that move in the favourable direction will be likely to move further in the same direction, and those moving downwards will be likely to continue so doing.
Value Factor Mutual Funds
Value factor mutual funds are mutual funds that invest in stocks or assets which are considered to be undervalued in relation to their underlying attributes. They utilise the value investing approach, which is that some stocks are more valuable than their market price due to short-run factors or market inefficiencies, and these stocks will eventually outperform as their market price catches up.
Low Volatility Strategy Funds
Low volatility strategy funds are mutual funds or exchange-traded funds (ETFs) that invest in stocks or assets that are less price volatile. They aim to provide stable returns by investing in securities that are less price volatile compared to the market as a whole. The goal is to reduce risk while providing consistent performance, particularly during market volatility.
Systematic Investing Models
Systematic investment models are investment approaches that are founded on predetermined, rules-based systems instead of discretionary or individual choice by fund managers. Systematic models utilise quantitative methods, which are typically derived from past data, statistical models, and algorithms to select investments. Systematic investing seeks to eliminate emotional bias and human errors from the investment process to provide a more disciplined and uniform approach.
Please share your thoughts on this post by leaving a reply in the comments section. Contact us via Phone, WhatsApp, or Email to learn more about mutual funds, or visit our website https://bfccapital.com/ .
Alternatively, you can download the Prodigy Pro app to start investing today!
Disclaimer – This article is for educational purposes only and does not intend to substitute expert guidance. Mutual fund investments are subject to market risks. Please read the scheme-related document carefully before investing.