Fixed Income Mutual Fund
With the markets being dynamic, fixed income mutual funds are like a lighthouse providing directional stability to investors in the ever-changing tides of these financial seas. However, moving around this landscape requires an understanding of the basics, from the types of bonds in these funds to the risks they carry.
This blog provides you with a complete guide on your way to achieving financial stability through fixed-income investments.
Fixed Income Mutual Funds: Achieving Stable Returns Through Bonds and Debt Securities
Let’s say you’re looking to make a stable, reliable income stream, like collecting rent from an apartment you own. But rather than purchasing an apartment, you’re buying “IOUs” ( I Owe You, a written document) known as bonds.
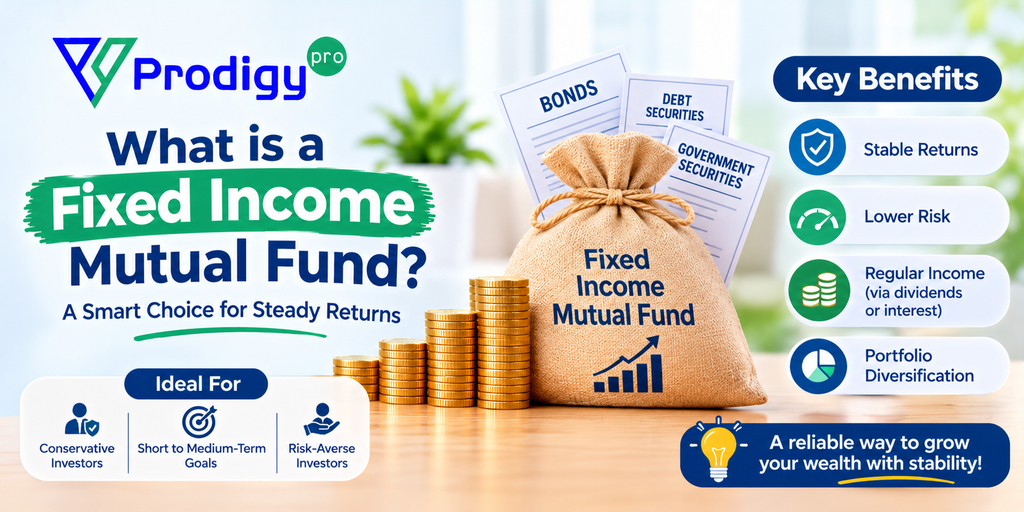
A fixed-income mutual fund is an investment vehicle where money from various investors is pooled together to invest mostly in bonds. So, to simplify, here is a fixed-income mutual fund:
- Bonds are IOUs: If a government or company needs to borrow money, it issues bonds. When you buy a bond, you are effectively lending money to the issuer, which agrees to repay the principal along with interest over a specified period.
- Fixed Income: The interest payments you get from bonds are typically “fixed.” This allows your income to be more predictable.
- Mutual Fund: Rather than purchasing separate bonds, a fixed-income mutual fund collects funds from many investors and buys a basket of bonds.
- Stable Returns: These funds aim to deliver steady income and safeguard your money (the amount you invested). They are generally seen as less risky than stock mutual funds, which can vary wildly.
- Debt Securities: “Debt securities” is a broad term that includes bonds and similar instruments, such as certificates of deposit (CDs) and Treasury bills. Essentially, these are financial instruments through which governments or companies raise funds by borrowing from investors.
How it works:
- You put money into a fixed-income mutual fund.
- That money is used by the fund manager to purchase a range of bonds and debt securities.
- The bonds yield interest, and the fund passes that income on to you and the other investors.
- The fund manager buys and sells the bonds that sit in the fund.
It’s like you’re part of a group of people who loan money to governments and companies. You receive your prorated share of the interest payments, and a professional manager takes care of all the details.
Simply put, bond mutual funds help investors attain stable returns.
Key Features and Advantages of Fixed Income Mutual Funds
The features and advantages of fixed income mutual funds are:
- Align with Long-Term Objectives: The fund can be analysed to help with the long-term financial goal, as it is a rather peaceful growth stream.
- Flexibility and Adaptability: Just like other mutual funds, investors have the option to switch to another fixed income scheme of the same fund house according to their evolving requirements or market conditions.
- Lump Sum and Systematic Investments: It provides flexibility in investing lump sums or through periodic investments (like SIPs), as most of these funds allow.
- Regular Transfers: Some schemes allow periodic transfers to other funds, which may help manage the risk in the long run.
- Tax Advantage (at Redemption): Taxation is levied only at the time of redemption of the investments.
- Short-Term Capital Gains (STCG): In case the holding period of the investment is less than 3 years, the gain is taxed under the income tax slab of the investor.
- Long-Term Capital Gains (LTCG): If the investment is held for more than 3 years, the profits are taxed under Long-Term Capital Gains tax.
- No Lock-in Period: In most cases, fixed income mutual funds do not carry a lock-in period, offering investors liquidity to exit from the scheme at their convenience.
Although these are considered less risky than equity funds, they’re still subject to interest rate risk, credit risk, liquidity risk, etc. Investors need to evaluate their risk tolerance and financial objectives before investing
Understanding Credit Risk, Interest Rate Risk, and Duration in Fixed Income Funds
Let’s check out some of the risks in fixed-income funds:
- Credit Risk (Will they pay me back?)
Credit risk is the possibility that the company or government that issued the bond may be unable to repay the money you lent.
It is similar to lending money to a friend: if they are financially stable, you feel confident they will repay you. However, if they are struggling financially, you may begin to worry about getting your money back.
Credit rating agencies, such as Moody’s and S&P, assess a borrower’s likelihood of default and assign ratings—AAA indicates a very low credit risk, while D indicates default. A diversified bond fund can help reduce the impact of any single issuer defaulting.
- Interest Rate Risk (Will my bond go down in value?)
If interest rates rise, newly issued bonds pay more in interest. Interest rates are what determine your coupon (the fixed interest you receive) on your bonds, so your older bonds (the bonds you purchased for lower interest rates) become less attractive overall and lose value.
Now, say you purchased a 3% interest bond. If new bonds begin paying 5%, everyone will want those newer bonds, and the price of your 3% bond will probably drop.
- Duration (How sensitive is my bond to interest rate changes?)
Duration measures how sensitive a bond’s price is to changes in interest rates. Bonds with longer durations are generally more sensitive to interest-rate movements than those with shorter durations.
In other words, when interest rates change, the price of a higher-duration bond tends to fluctuate more than that of a lower-duration bond. A longer duration indicates greater interest-rate risk.
Different Types of Fixed Income Mutual Fund Schemes in India
- Long-term debt funds
- Short-term debt funds
- Floating rate funds
- Credit opportunity funds
- Gilt funds
- Liquid funds
- Dynamic bond funds
Features of Fixed-Income Mutual Funds:
- Debt funds: They invest in more secure debt instruments like government bonds, corporate bonds, debentures, and other securities.
- Money market funds: These funds invest in short-term, highly liquid instruments (e.g., Treasury bills, commercial paper, short-term certificates of deposit (CDs) of banks).
- Exchange-traded funds (ETFs) — Index funds that are traded on stock exchanges.
Evaluating Fixed Income Fund Performance:
To evaluate fixed-income funds, investors use several metrics that assess returns, risk levels, and overall efficiency. To determine how well a fund is meeting its investment objectives, they typically consider both quantitative and qualitative factors.
- Total return: The total return represents the sum of interest income, capital gains, and fund net asset value (NAV) changes over a period.
- Yield to maturity (YTM): The total return expected on a bond if the bond is held until the maturity date.
- Sharpe ratio: Evaluates the risk-adjusted return of a fund.
- Minimum Market Return: The Market Minimum Return compares a fixed-income fund’s performance against relevant benchmarks, such as bond indices.
How Do Fixed Income Funds Offer Stable Returns and Manage Risk?
Let’s discuss how these bond funds strive to strike a balance between safety and liquidity:
- Preservation of capital: The goal of the fund is primarily to keep you from losing your initial investment by seeking stability over superior returns. Funds that invest in fixed income do so by purchasing bonds viewed as relatively safer, such as government bonds or corporate bonds from top-rated companies.
- Liquidity: Liquidity is how easily you can get your cash investment. The liquidity of fixed-income mutual funds is quite high. You can usually sell your fund shares and have your money returned to you with relative speed. This contrasts with a certificate of deposit (CD), for example, where you’d have to wait until it matures to access your money without incurring penalties.
- Stable Returns: Bonds pay regular income in the form of interest payments. These stable income figures are passed on to you by fixed income funds, resulting in a more predictable investment return. That’s like just getting a regular paycheck.
- Investment strategy: They spread out the fund’s holdings to lessen the impact of any one bond that isn’t paid off. They also track interest rates and adjust the holdings in the portfolio to reduce interest rate risk.
Key Factors for Investors in Fixed Income Mutual Funds
Here are the specifics on what to watch for when choosing a bond fund:
- Fund Management: This is the team that decides where to invest. A good manager understands bonds and risk.
- NAV: Net Asset Value (NAV is the price per fund share. That amount varies each day as the bond values are adjusted.
- Expense Ratios: These are the running costs of the fund expressed as a percentage. And more money for you with lower fees.
Basically: Check who’s running the fund. Know the daily price. Pay attention to the fees.
Also, Check – What Are Open-Ended Mutual Funds
On a parting note…
Fixed-income mutual funds are essential for investors looking for stability and predictable returns in the face of market volatility. A healthy balance of diverse financial instruments, from sovereign bonds to yield-maximising assets, provides a diversified portfolio balancing yield with risk. Also, the emphasis on capital preservation and liquidity highlights the fund’s function as a safe and liquid investment. Investors gain insights into the mechanics of their investments, and by keeping fund management, NAV, and expense ratios in mind, they can make informed decisions to navigate this space — using fixed income mutual funds to neutralise risk and optimise returns, creating a diversified portfolio capable of weathering market volatility while generating steady cash flow.
These funds provide a strategic path to these goals, showing how careful bond investment can be an important part of a balanced approach to investing.
Please share your thoughts on this post by leaving a reply in the comments section. Contact us via phone, WhatsApp, or email to learn more about mutual funds, or visit our website. Alternatively, you can download the Prodigy Pro app to start investing today!learn more about mutual funds, or visit our website. Alternatively, you can download the Prodigy Pro app to start investing today!
How much credit risk is there in a bond fund?
The danger is that the bond issuer will default on the debt.
What impact do interest rate changes have on the values of bond funds?
Bond prices usually move in the opposite direction of interest rate shifts.
What is “duration,” as it relates to a bond fund?
The fund’s exposure to changes in interest rates.
What is an expense ratio to a bond fund?
The fees you are billed that pay to managing the fund every year.
Disclaimer: This article is for educational purposes only and does not intend to substitute expert guidance. Mutual fund investments are subject to market risks. Please read the scheme-related document carefully before investing.